Why the Fenton Farmers Market Is One of My Favorite Parts of SummerBy Marissa Mayberry, The Pink Realtor If you’ve lived in Fenton for any length of time, you already know that Thursdays
Dated: March 5 2024
Views: 195
If you want to buy a home, you should know your credit score is a critical piece of the puzzle when it comes to qualifying for a mortgage. Lenders review your credit to see if you typically make payments on time, pay back debts, and more. Your credit score can also help determine your mortgage rate. An article from US Bank explains:
“A credit score isn’t the only deciding factor on your mortgage application, but it’s a significant one. So, when you’re house shopping, it’s important to know where your credit stands and how to use it to get the best mortgage rate possible.”
That means your credit score may feel even more important to your homebuying plans right now since mortgage rates are a key factor in affordability. According to the Federal Reserve Bank of New York, the median credit score in the U.S. for those taking out a mortgage is 770. But that doesn’t mean your credit score has to be perfect. The same article from US Bank explains:
“Your credit score (commonly called a FICO Score) can range from 300 at the low end to 850 at the high end. A score of 740 or above is generally considered very good, but you don’t need that score or above to buy a home.”
Working with a trusted lender is the best way to get more information on how your credit score could factor into your home loan and the mortgage rate you’re able to get. As FICO says:
“While many lenders use credit scores like FICO Scores to help them make lending decisions, each lender has its own strategy, including the level of risk it finds acceptable. There is no single “cutoff score” used by all lenders and there are many additional factors that lenders may use to determine your actual interest rates.”
If you’re looking for ways to improve your score, Experian highlights some things you may want to focus on:
Finding ways to make your credit score better could help you get a lower mortgage rate. If you want to learn more, talk to a trusted lender.
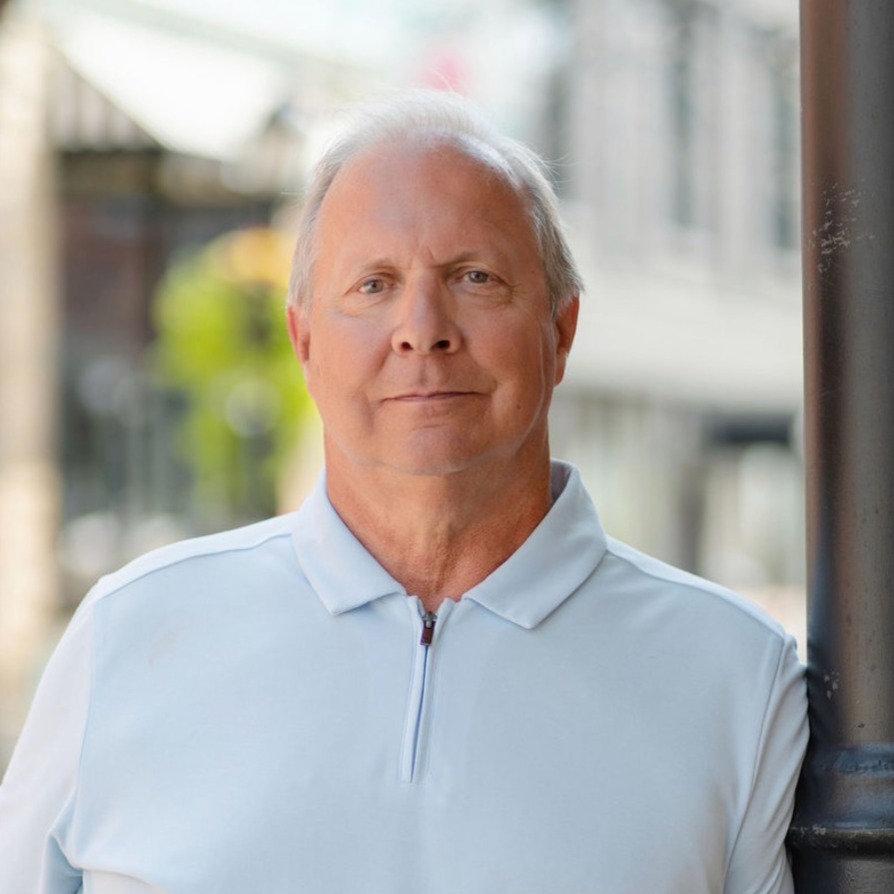
Married for 50 years in June 2025 to Sharon. Father of 3 grown children, with 11 grandchildren, life long resident of Fenton, Michigan. U.S. Army veteran serving in the Military Police. Father was....
Why the Fenton Farmers Market Is One of My Favorite Parts of SummerBy Marissa Mayberry, The Pink Realtor If you’ve lived in Fenton for any length of time, you already know that Thursdays
Should You Buy First or Sell First? A Guide for Homeowners Making a MoveIf you're planning to move, one of the biggest questions you'll face is: Should you buy your next home first, or sell
🌷 March Home Maintenance Tips to Get Your Home Spring-ReadyAs winter fades and spring approaches, March is the perfect time to give your home a little attention. A few simple maintenance tasks
The Benefits of a Home Warranty for Both Sellers and BuyersWhen buying or selling a home, there are a lot of moving parts — inspections, appraisals, negotiations, and financing. One tool that
 IDX provided courtesy of Realcomp II Ltd., via REMAX Platinum and The Originating MLS(found above), © 2026 Realcomp II Ltd. Shareholders. The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Data is updated as of September 26, 2026 12:12 PM UTC Information deemed reliable but not guaranteed.
The data relating to real estate on this
web site comes in part from the Internet Data Exchange (IDX) Program of Realcomp Ltd. Real estate listings held by firms other than REMAX Platinum are marked with the Realcomp Internet Data Exchange logo or thumbnail logo and detailed information about them includes the Listing Broker's Firm Name.
The information being provided is for consumers personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing.
Show More...
 Provided through IDX via MiRealSource. Courtesy of MiRealSource Shareholder. Copyright MiRealSource.
The information published and disseminated by MiRealSource is communicated verbatim, without change by MiRealSource, as filed with MiRealSource by its members. The accuracy of all information, regardless of source, is not guaranteed or warranted. All information should be independently verified.
Copyright 2026 MiRealSource. All rights reserved. The information provided hereby constitutes proprietary
information of MiRealSource, Inc. and its shareholders, affiliates and licensees and may not be reproduced or transmitted in any form or by any means, electronic or mechanical, including photocopy, recording, scanning or any information storage and retrieval system, without written permission from MiRealSource, Inc.
Provided through IDX via MiRealSource, as the "Source MLS", courtesy of the Originating MLS shown on the property listing, as the Originating MLS. The information published and disseminated by the Originating MLS is communicated verbatim, without change by the Originating MLS, as filed with it by its members.
The accuracy of all information, regardless of source, is not guaranteed or warranted. All information should be independently verified.
Copyright 2026 MiRealSource. All rights reserved. The information provided hereby constitutes proprietary information of MiRealSource, Inc. and its shareholders, affiliates and licensees and may not be reproduced or transmitted in any form or by any means, electronic or mechanical, including photocopy, recording, scanning or any information storage and retrieval system, without written permission from MiRealSource, Inc.
Show More...
